Denied claims / Shingle roof

Shingle roof claim denied?

Most shingle denials come down to one thing: the adjuster didn't see enough proof that the storm caused the damage. Hail bruises and wind-creased shingles are easy to miss from a ladder, and easy to write off as age.

Why shingle roof claims get denied

These are the denial reasons we see most on asphalt shingle roofs, and what we do about each one.

"Wear and tear" or "age-related"

The adjuster says granule loss, cracking or curling is from age, not the storm. On an older roof, this is the most common denial there is.

What we do: We photograph fresh hail bruises next to the old weathering. Storm damage has sharp edges and exposed mat. Age wear is even and gradual. Side by side, the difference is clear.

"No hail damage found"

The adjuster walked the roof, chalked a few spots and found "not enough hits" per test square, or looked only from the ground.

What we do: We test every slope, mark each hit, and back it up with soft-metal dents on vents, gutters and AC fins, plus hail reports for your address and date.

"Wind damage is cosmetic"

No shingles blew off, so the claim gets denied. But a shingle that lifted and creased has lost its seal, even if it lay back down.

What we do: We lift-test shingles and document broken seal strips and creases at the nail line. A creased shingle can't be repaired, and many can't be matched either.

"Pre-existing" or "filed too late"

The insurer says the damage was there before the storm, or the claim missed the policy deadline.

What we do: We tie the damage to a specific storm date with weather data and the condition of the damage. Late claims aren't always dead either. Check your policy and your state's rules.
What we look for

Photos from our own inspections. This is the kind of documentation that supports a re-inspection. Results vary; no claim outcome is guaranteed.

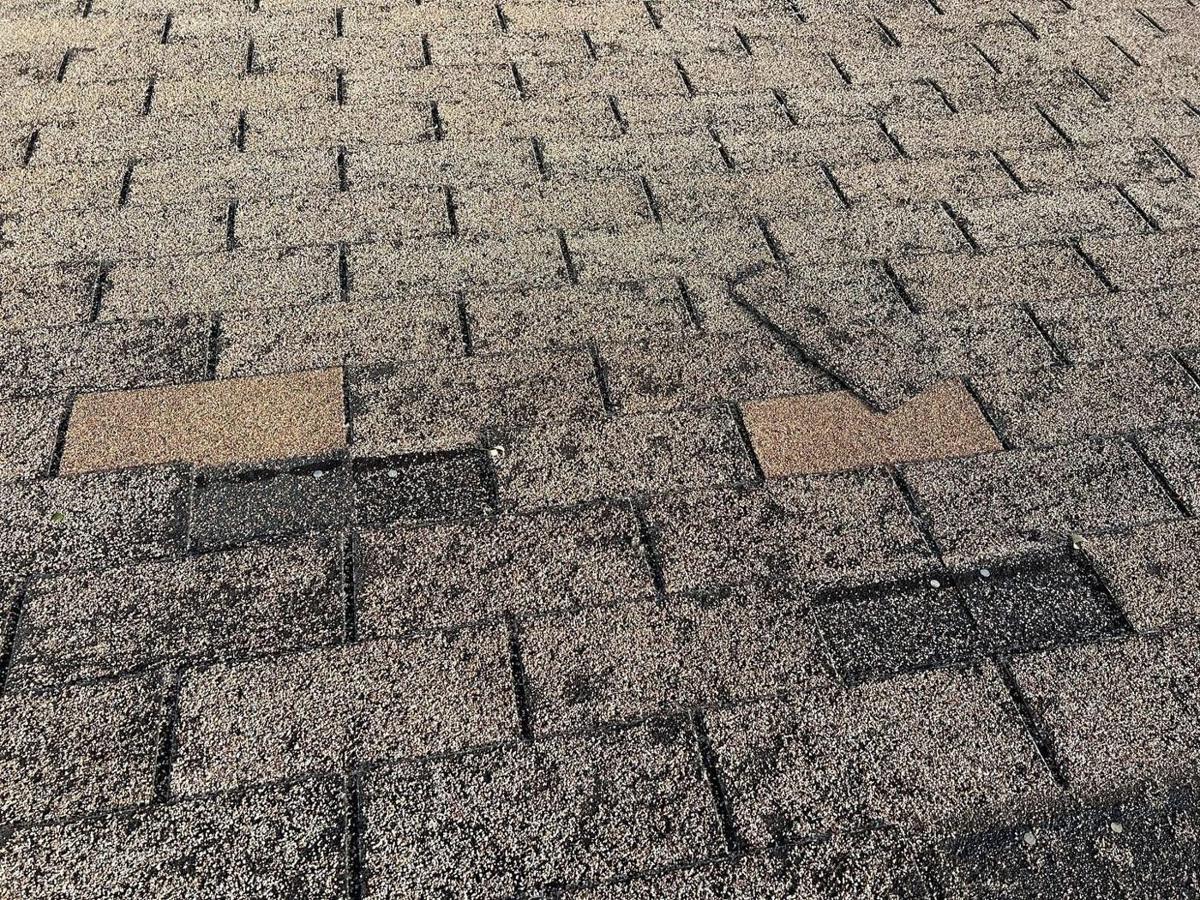
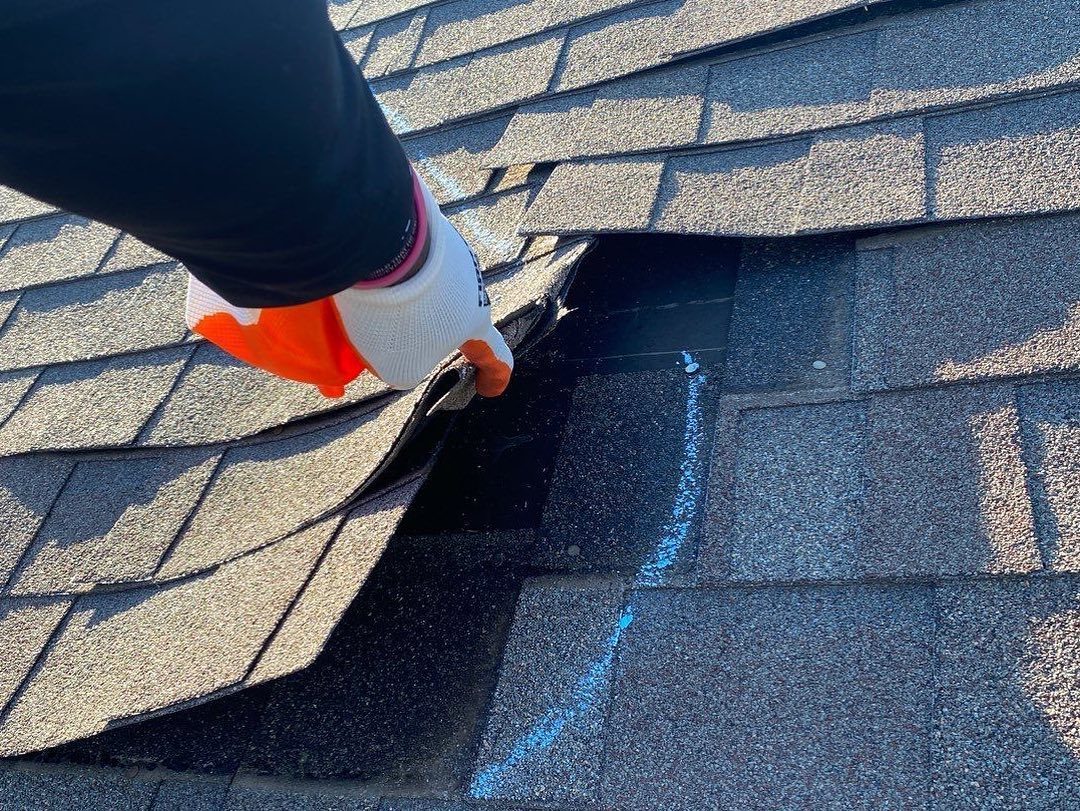
A wind-creased shingle. It lay back down, but the seal is broken.
Hail bruises with fresh granule loss on an asphalt shingle roof.
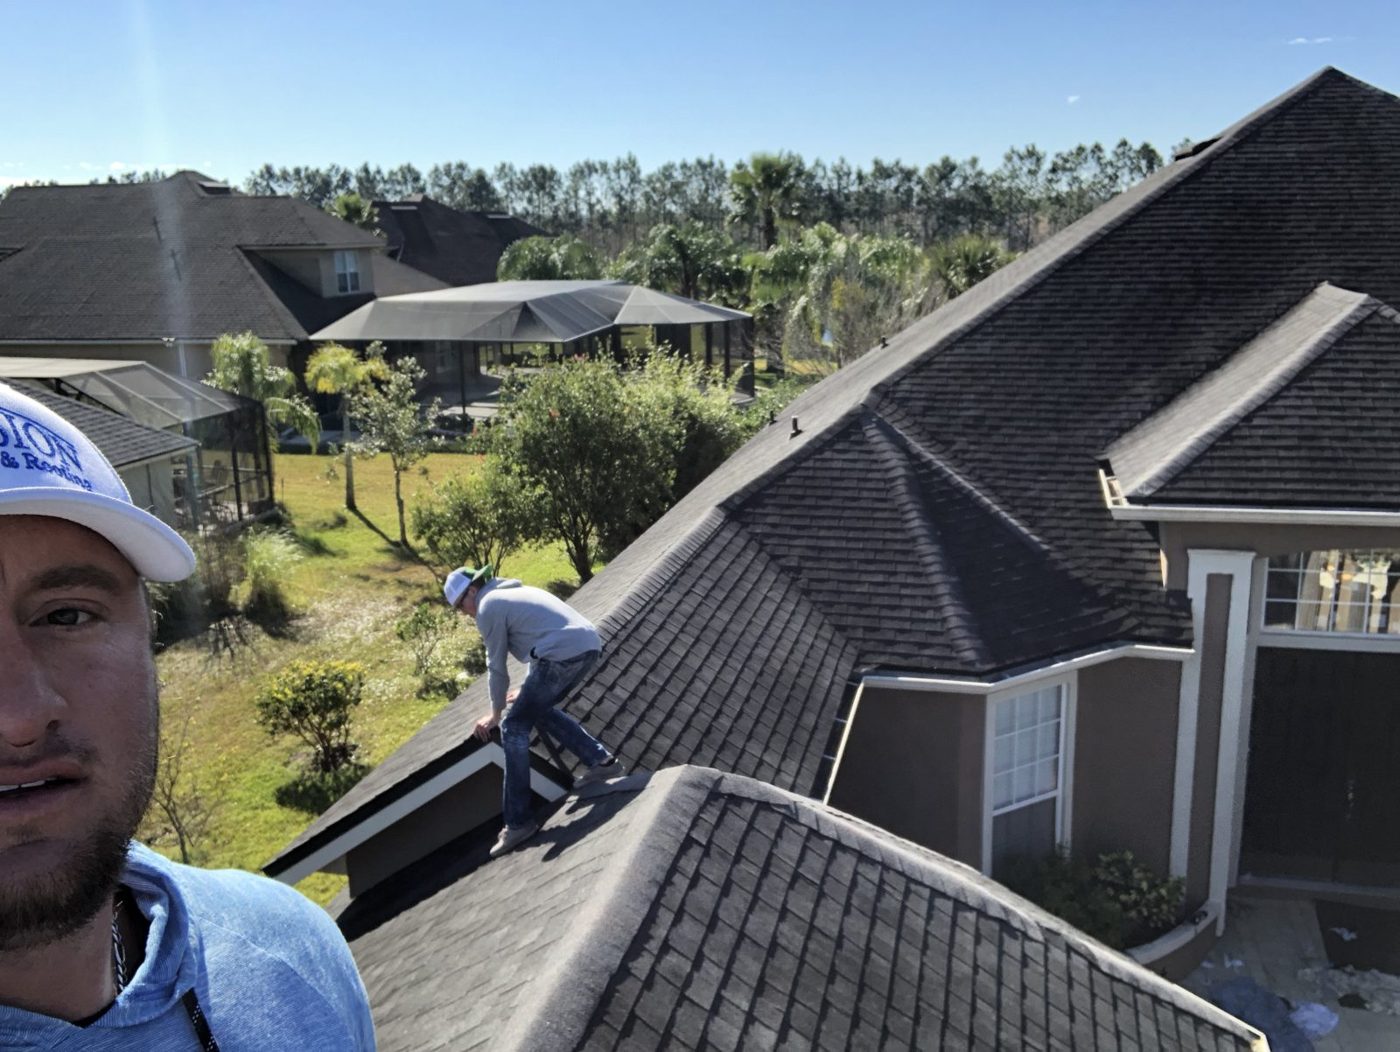
Our team walking every slope of a shingle roof after a storm.

What we do

A denial letter is the insurer's first answer, not always the final one.

Send us your denial letter

Text a photo of the letter and your roof, or upload them on our contact form. We'll tell you what we see and what your options are.

We re-inspect and document

We go over the whole roof and build a report with photos, measurements and weather data that ties the damage to the storm.

You decide your next step

Depending on your policy, your options may include a re-inspection with the adjuster, a supplement, or the appraisal clause. We inspect, document and write the repair scope, and meet the adjuster on the construction scope. SkyView Restoration Group is not a public adjuster or law firm. You may hire any licensed public adjuster or attorney, or none.

Got a denial letter?

Send it to us with a few photos of your roof. A real person on our team will look it over and tell you where you stand. Asking is free. If you later sign a Project Agreement, its fee and cancellation terms are at SkyViewRestore.com/terms.

Call now Text a photo